The combination of solid financial returns and clear, measurable social impact makes financial inclusion a compelling investment theme for pension funds and other institutional investors, according to Crijns.
“The primary objective of pension funds, after all, is to secure good long-term returns for pensioners. Microfinance loans tend to show little correlation with global market sentiment, which is helpful to diversify long-term performance of large portfolios. Historically, when markets went up, microfinance returns were stable. When markets went down, microfinance returns were stable.”
Building resilience through financial inclusion
Working with local financial service providers
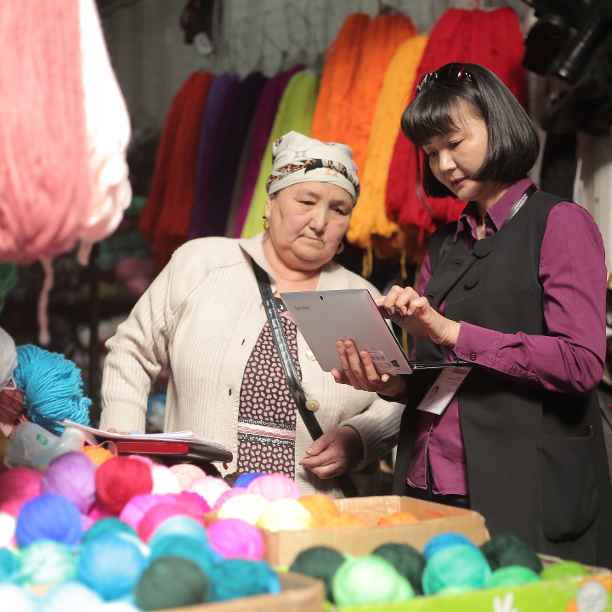
Triodos Investment Management does not provide thousands of small loans directly around the world. Instead, it lends to a carefully selected group of local financial institutions with strong local knowledge and expertise. These institutions then lend the money to individuals and small businesses that have limited or no access to conventional banks. This could be a small-scale farmer buying seeds or an entrepreneur purchasing additional machinery. In this way, the money reaches people who use it to finance real economic activity.
Through Triodos Microfinance Fund, investors gain access to a globally diversified portfolio of these financial institutions.
When selecting partners, Triodos Investment Management’s in-house investment team assesses a range of factors, including the financial soundness of local institutions, their lending policies, consumer protection practices and the way they put their social objectives into practice. Country risk is also an important part of the assessment. Exposure limits are set for each country based on objective data.
Stable returns and limited credit losses
This approach results in an attractive risk-return profile. Since its launch in 2009, Triodos Microfinance Fund has delivered a net annual return of between 4% and 5%. Over the past twenty years, the strategy has had only one negative year: 2020, during the COVID-19 pandemic. That decline was not caused by correlation to global markets, but by local lockdowns.
That loss was more than offset in the following year. Once local lockdowns were lifted, business activity resumed and repayments restarted, which allowed provisions to be reversed. Crijns notes that the return may seem modest in view of the perceived emerging markets risks, but says it should be assessed against the relatively lower risk of financial inclusion. “The fund has a very low default rate, which shows that the risks linked to financial inclusion are lower than many people assume for emerging markets.”
The average default rate on loans provided by Triodos Microfinance Fund to financial institutions is just 0.18% per year. The underlying microfinance institutions act as risk buffer for financial inclusion investments: they select borrowers and absorb losses on individual loans themselves. As a result, investors are exposed only to the credit risk of regulated local financial institutions, which are typically supervised by the central bank.
Diversification benefits
This approach also makes this form of financial inclusion fundamentally different from investing in listed companies in emerging markets. With equities, investors remain exposed to stock market valuations, market sentiment and company-specific risks.
Crijns points to an example from 2022 to show how this can work in practice. An asset manager had included the fund in a model portfolio. “That year, we received positive feedback: without our investment in Triodos Microfinance Fund, our portfolio would have recorded a 15% loss in 2022, but thanks to the position in the fund, the loss was limited to 5%.”
According to Crijns, the low correlation with financial markets is easy to explain. “Ultimately, the money reaches people locally. A small-scale farmer producing for the local market, or a trader at a market in Ghana, is unlikely to be directly affected by a stock market crisis elsewhere in the world. They produce and trade essential goods and services that remain in demand during economic downturns.”
Broad geographic diversification within the financial inclusion portfolio helps reduce risks further. Triodos Investment Management uses a country-risk framework that takes account of factors such as macroeconomic conditions, sovereign debt, levels of corruption and climate risk. The higher the risk, the lower the maximum exposure to any single country. The highest-risk countries are excluded.
Measurable social impact
Financial inclusion gives pension funds the opportunity to achieve clear and measurable social impact. It offers financial services to households and small businesses that are excluded from the conventional banking system, with particular attention to women and people in rural areas. In this way, financial inclusion relates to several United Nations Sustainable Development Goals, including SDG 5 (gender equality), SDG 8 (economic growth) and SDG 10 (reduced inequalities). “It may also support poverty reduction indirectly, although that is not an objective in itself, by giving more people the opportunity to earn an income, grow a business and contribute to the economic development of their region.”
The social impact is highly tangible. In many countries, women and people in rural areas have less access to conventional financial services. Triodos Microfinance Fund therefore reports on indicators such as the number of clients reached, the percentage of women and the percentage of clients in rural areas. The average loan amount is around EUR 2,000, although this varies significantly by region.
Crijns: “Through financial inclusion, we can make a real difference in people’s lives, particularly for women and people in remote regions. And no, that impact does not come at the expense of returns. Over the past twenty years, investments in financial inclusion have shown little to no evidence of a trade-off between impact and return. On the contrary, financial inclusion has offered stable returns, low correlation and meaningful diversification benefits for any portfolio.”
Disclaimer
This is a marketing communication. When investing in the fund, please take into account all the characteristics and/or objectives of the promoted fund as described in its prospectus. Further, please take notice of the sustainability aspects of the fund as found here. Please refer to the prospectus and the Key Information Document of Triodos Microfinance Fund before making any final investment decisions. An English summary of investor rights can be found here. The value of your investment can fluctuate because of the investment policy. Triodos Microfinance Fund is managed by Triodos Investment Management. Triodos Investment Management holds a license as alternative investment fund manager and UCITS manager and is under the supervision of the Autoriteit Financiële Markten and De Nederlandsche Bank in the Netherlands. Triodos Investment Management may decide to stop the marketing of its collective investment schemes in your country.”